Goodwill Donation Centers: The Legal and Tax Basics
Goodwill's bins accept more than old sweaters. Here's how the nonprofit network works, what your receipt must say, and how to value what you give.
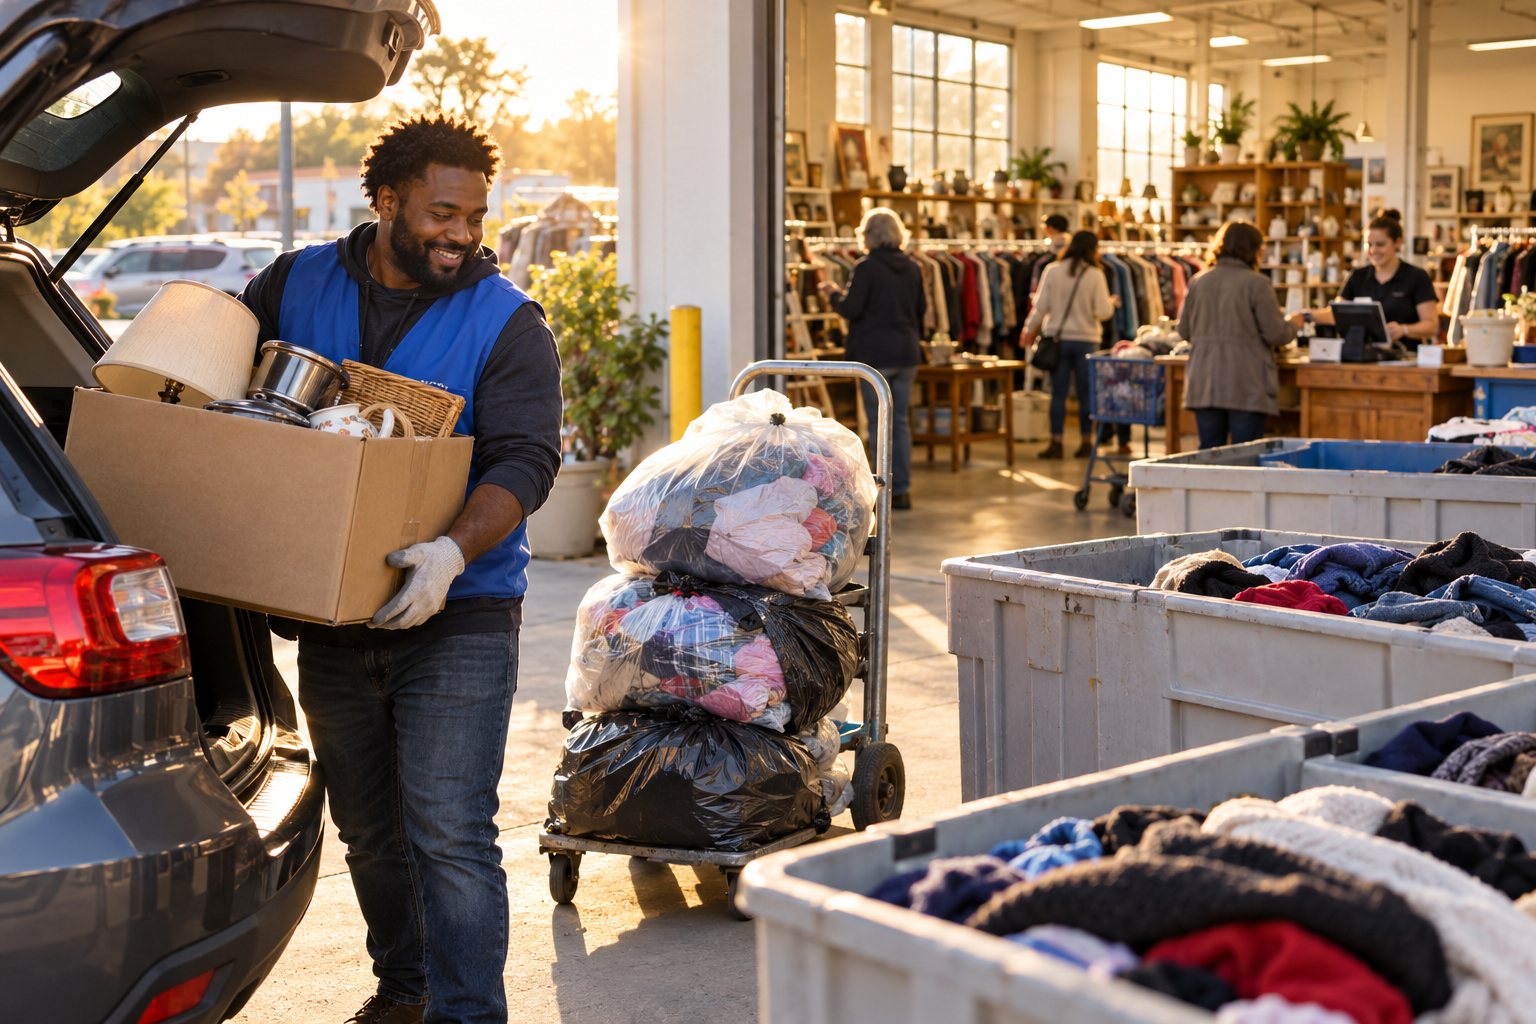
A car pulls up to the covered bay, the trunk opens, and a teenager in a blue vest hauls out four bags of clothes and a microwave. The driver gets a blank receipt and pulls away. That thirty-second exchange is one of the most common encounters ordinary Americans have with a tax-exempt organization — and one of the most misunderstood. Goodwill donation centers are not a single company, not a government program, and not a garbage service with better branding. They are the front door of a specific legal structure, and knowing how that structure works protects both your wallet and the charity.
The nonprofit structure behind the sign
Goodwill Industries International is a membership association, not a chain of stores. Its U.S. and Canadian members are roughly 150 independent local organizations, each separately incorporated and each holding its own 501(c)(3) tax-exempt status. The Goodwill in Columbus operates under different directors, files different Form 990s, and answers to different state regulators than the one in Seattle. That decentralization matters to donors: your receipt comes from a specific legal entity, and that entity — not the national brand — is the one the IRS recognizes.
The business model is unusual among charities. These organizations collect donated goods for free, sell them in thrift stores, and use the proceeds to fund job training, career counseling, and placement programs. Retail revenue is not a side hustle; it typically covers the majority of a local Goodwill's operating budget. Store sales are exempt from federal income tax but generally not from state and local sales tax, and the retail operations must be substantially related to the charitable mission to avoid unrelated business income tax problems.
What makes a donation tax-deductible
Three conditions have to line up. First, you must itemize deductions rather than take the standard deduction. Since the standard deduction rose sharply in 2018, most households no longer itemize, which means most donations produce no federal tax benefit at all — a fact worth knowing before you spend an hour sorting receipts. Second, the property must be in good used condition or better; clothing and household goods that are torn, stained, or broken are not deductible, and the IRS can disallow a deduction even if the charity accepted the item. Third, you must have proper substantiation.
Under $250
You need a receipt or a reliable written record: the charity's name, the date, and a description of what you gave. A bank record or a dated drop-off receipt is usually enough. Photographing your donation before you hand it over is a cheap habit that resolves a lot of later arguments.
$250 to $500
Here the rules tighten. For any single contribution of $250 or more, you must obtain a contemporaneous written acknowledgment from the charity before you file your return. It must state whether you received any goods or services in exchange — usually "no" — and describe the property contributed. A drop-box receipt that shows only a date and a logo typically fails this test. If you donated a couch and got a pickup, ask whether the pickup counts as a service; it usually does not, but the acknowledgment has to say so explicitly.
Over $500
Total noncash contributions above $500 require Form 8283, Section A, attached to your return, listing how you acquired each item and your claimed value. If a single item — or a group of similar items — is valued above $5,000, Section B applies and generally requires a qualified appraisal. A single item of clothing or a household item claimed at more than $500 needs an appraisal attached to the return.
Valuation: why the number in your head is usually wrong
The deduction is the item's fair market value — what a willing buyer would pay for it in its present condition, in that market. For donated clothing and furniture, that means thrift-store prices, not what you paid at retail and not what it would cost to replace new. The valuation guides floating around online are rough regional averages, not IRS tables, and using them as a ceiling rather than a starting point is a common audit trigger.
- Itemize and document each item or bundle with a reasonable price.
- Keep your own dated list; the charity is not obligated to value anything for you.
- Charitable driving is deductible at 14 cents per mile, separate from the goods.
- Never claim a deduction for the value of your time or services.
What the centers accept — and what they don't
Most locations take clothing, shoes, books, housewares, small appliances, furniture, and electronics in working order. They typically refuse mattresses, cribs, car seats, recalled products, weapons, hazardous materials, and anything soiled. Those refusals are not just operational fussiness: selling a recalled crib or a used car seat can create product liability exposure for the nonprofit, and many states regulate the resale of used bedding and upholstered furniture.
If a donated item is clearly unsalable, the organization may still accept it and route it to textile recycling — but keep in mind that a donation the charity cannot sell is a donation with no fair market value, and therefore no deduction.
The drop-box problem
Not every metal bin with a charitable-sounding name belongs to a charity. For-profit clothing collectors sometimes use names and logos that mimic nonprofits, then sell the goods to exporters. A legitimate bin should display the organization's legal name and, in many states, a registration statement. Before donating anything valuable, verify the entity's 501(c)(3) status through the IRS Tax Exempt Organization Search and confirm the drop-off site is listed on the charity's own website.
If you want to build something similar
Founders sometimes ask how to replicate the model. The legal path runs through incorporation as a nonprofit corporation in your state, adoption of bylaws and conflict-of-interest policies, filing Form 1023 or 1023-EZ for federal exemption, registering for charitable solicitation in each state where you fundraise, and securing any local permits for retail or donation collection. Expect six to twelve months and real legal fees; the retail arm also brings sales tax, employment, and premises liability obligations that a pure grantmaking charity never faces.
The blue vest at the donation bay is the visible tip of a fairly elaborate legal arrangement. Treat the receipt like the financial document it is, value your goods honestly, and the transaction stays simple — which is exactly what it looks like from the driver's seat.